By Leen Shami
How Tamam Unlocked SAR 1.9M in Additional Monthly Profit by Strengthening Underwriting with Lean
Tamam is one of KSA's leading digital lenders, providing fast, accessible financing through a fully digital experience.
As digital lending has grown across the kingdom, so has the diversity of how people earn. A growing share of applicants draw income from freelance work, independent businesses, rental properties, commissions, and digital marketplaces. That income is real and recurring, but traditional data sources were never designed to see it. The result is a large, creditworthy population that lenders cannot confidently assess, and a market that remains largely untapped.
To underwrite this segment with confidence, Tamam partnered with Lean to bring verified financial data into its lending journey, enabling faster decisions and expanding responsible access to credit.
Challenge
Tamam reviews hundreds of thousands of loan applications every month, making both speed and accuracy essential to its underwriting process.
Like many lenders, Tamam relied on traditional data sources to assess affordability. While these remain an important part of underwriting, they primarily reflect registered salary sources and existing credit history. As applicant diversity grew, these datasets no longer captured the full picture of applicants' financial standing.
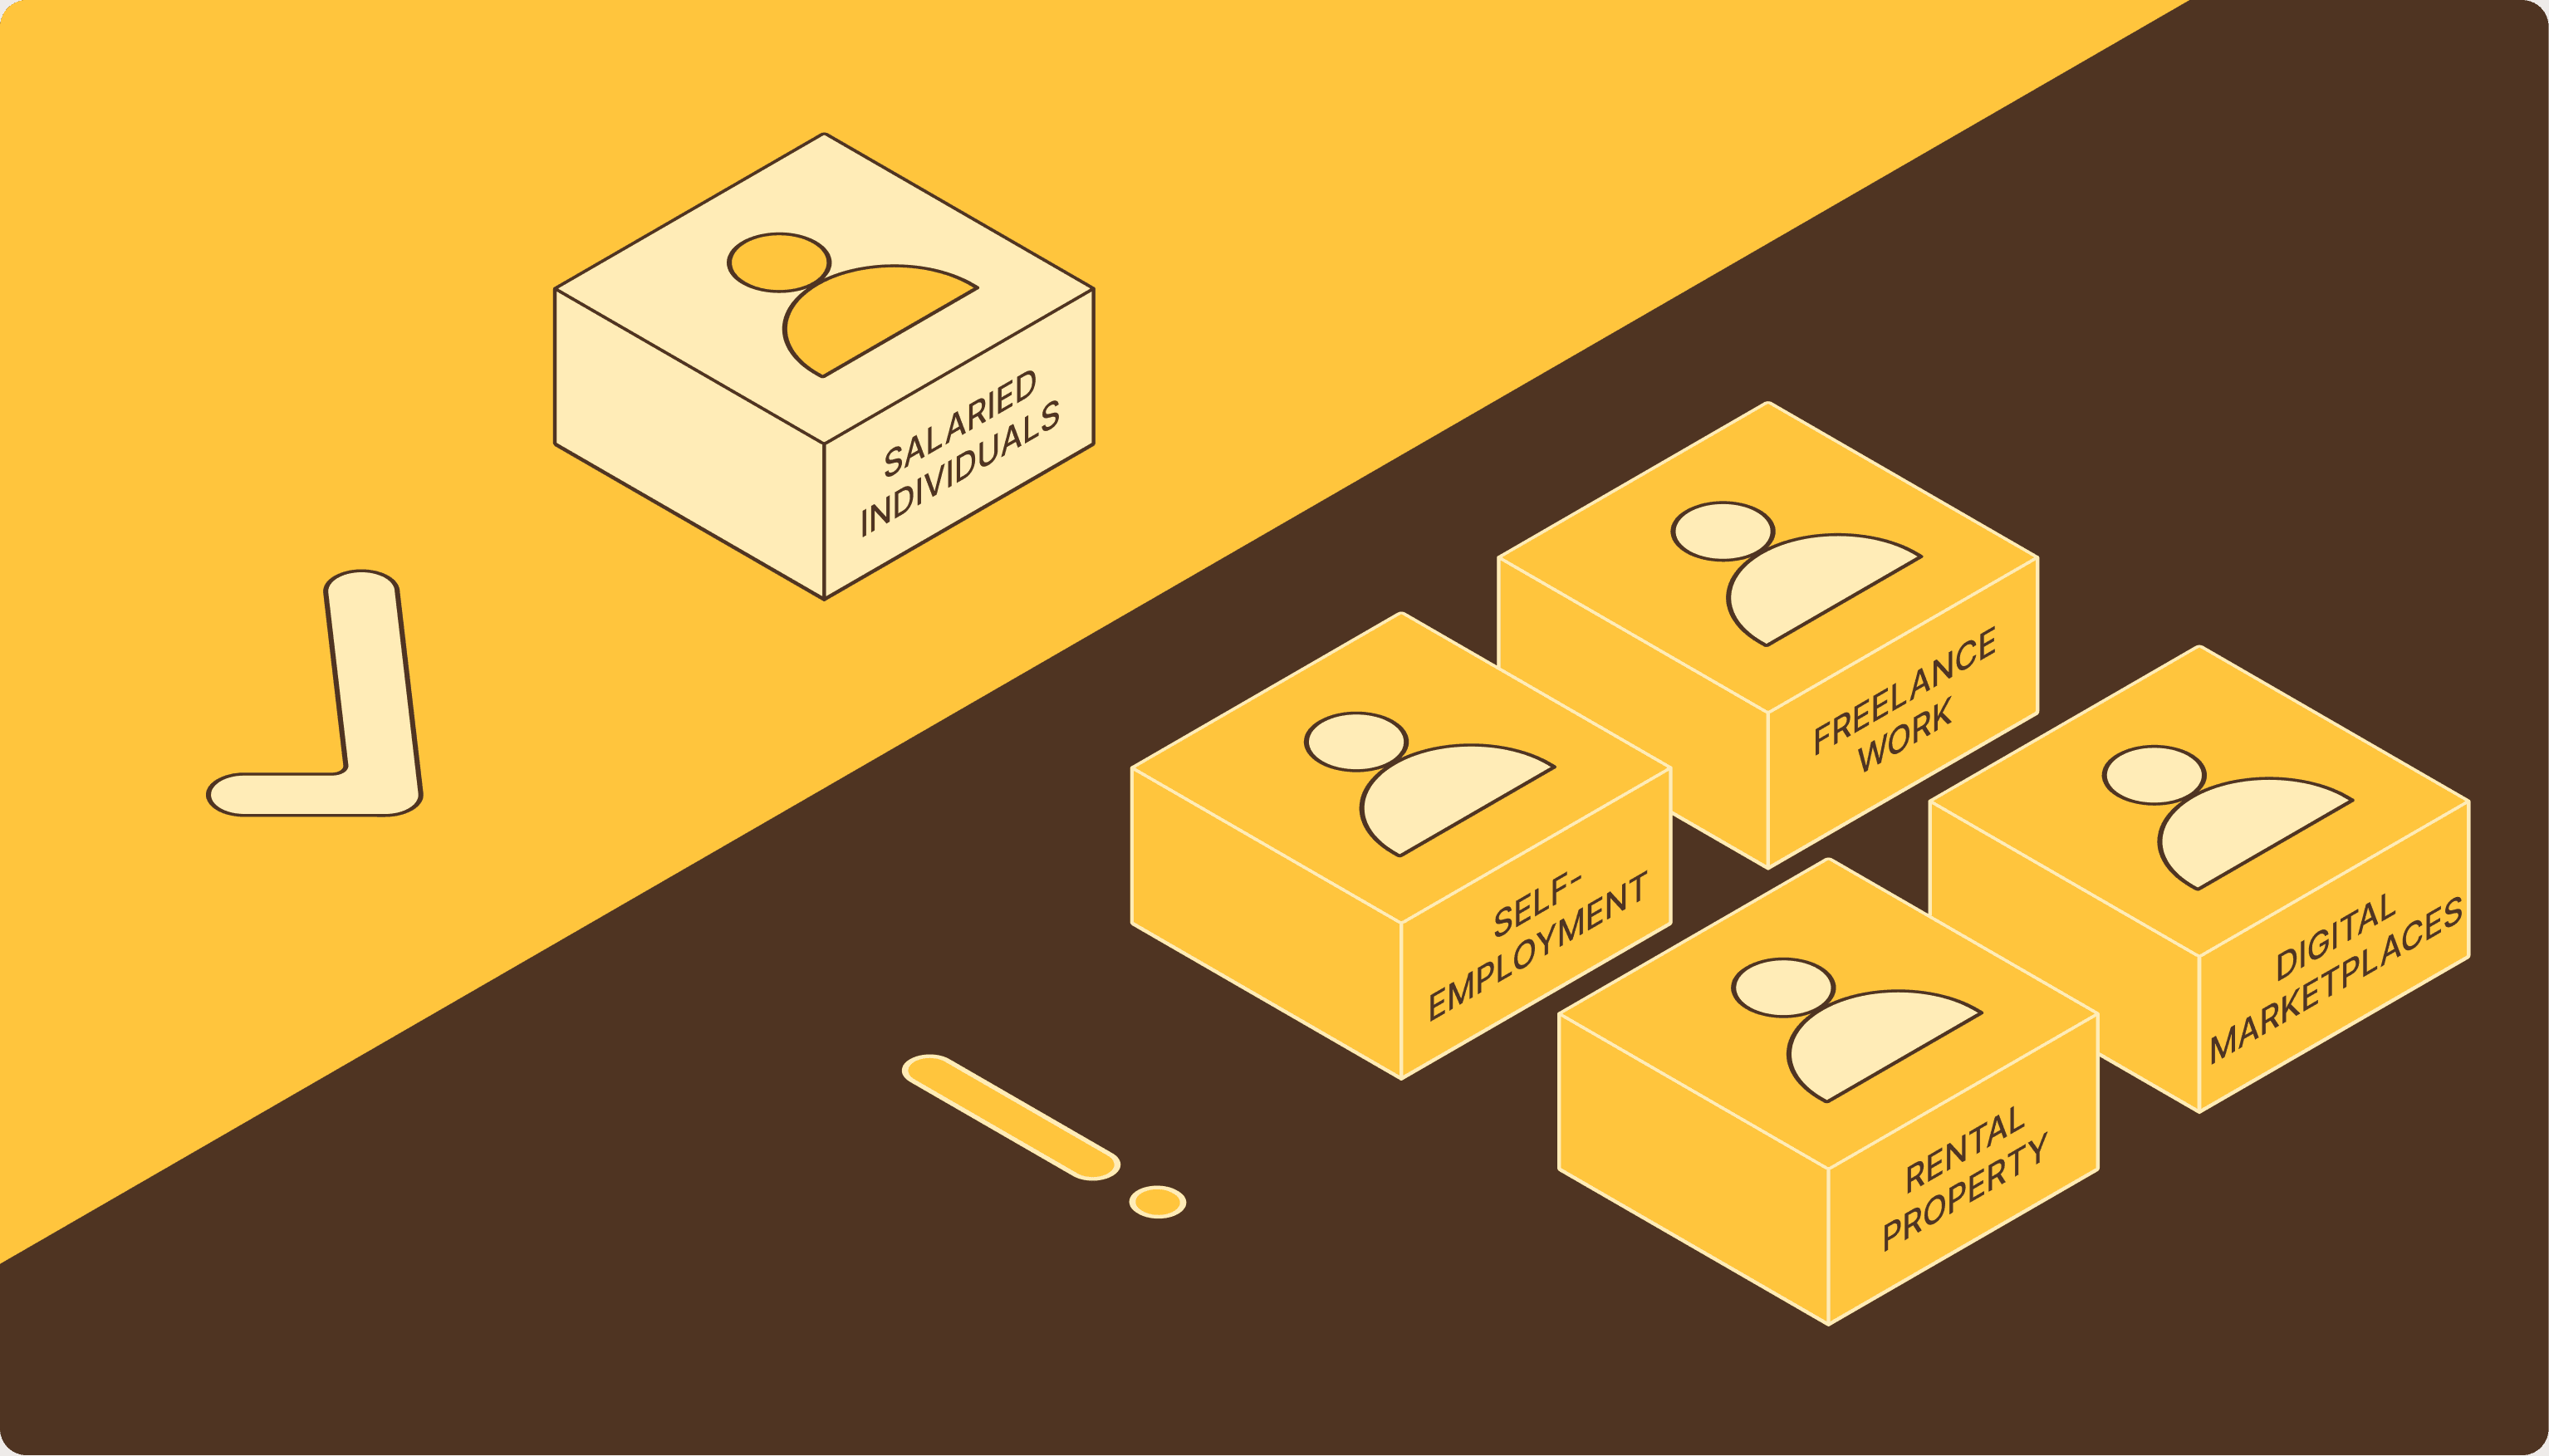
Applicants earning through self-employment, freelance work, rental property, or digital marketplaces often appeared less creditworthy than they were. The alternative was collecting and manually reviewing bank statements, adding operational overhead and friction to the lending journey while exposing Tamam to the risk of document tampering and defaulted repayments.
Tamam needed a scalable way to assess customers using a broader view of their income.
In summary, four constraints shaped its underwriting:
- Limited income visibility: Traditional data sources could not capture non-salaried income.
- Manual review at scale: Collecting and checking bank statements increased operational effort and slowed decisions.
- Fraud exposure: Self-submitted documents carry a risk of misrepresentation that is difficult to detect at volume.
- Missed lending opportunities: Customers with genuine repayment capacity were being overlooked.
Solution
To move beyond salary-based underwriting, Tamam integrated Lean's Insights into its lending journey.
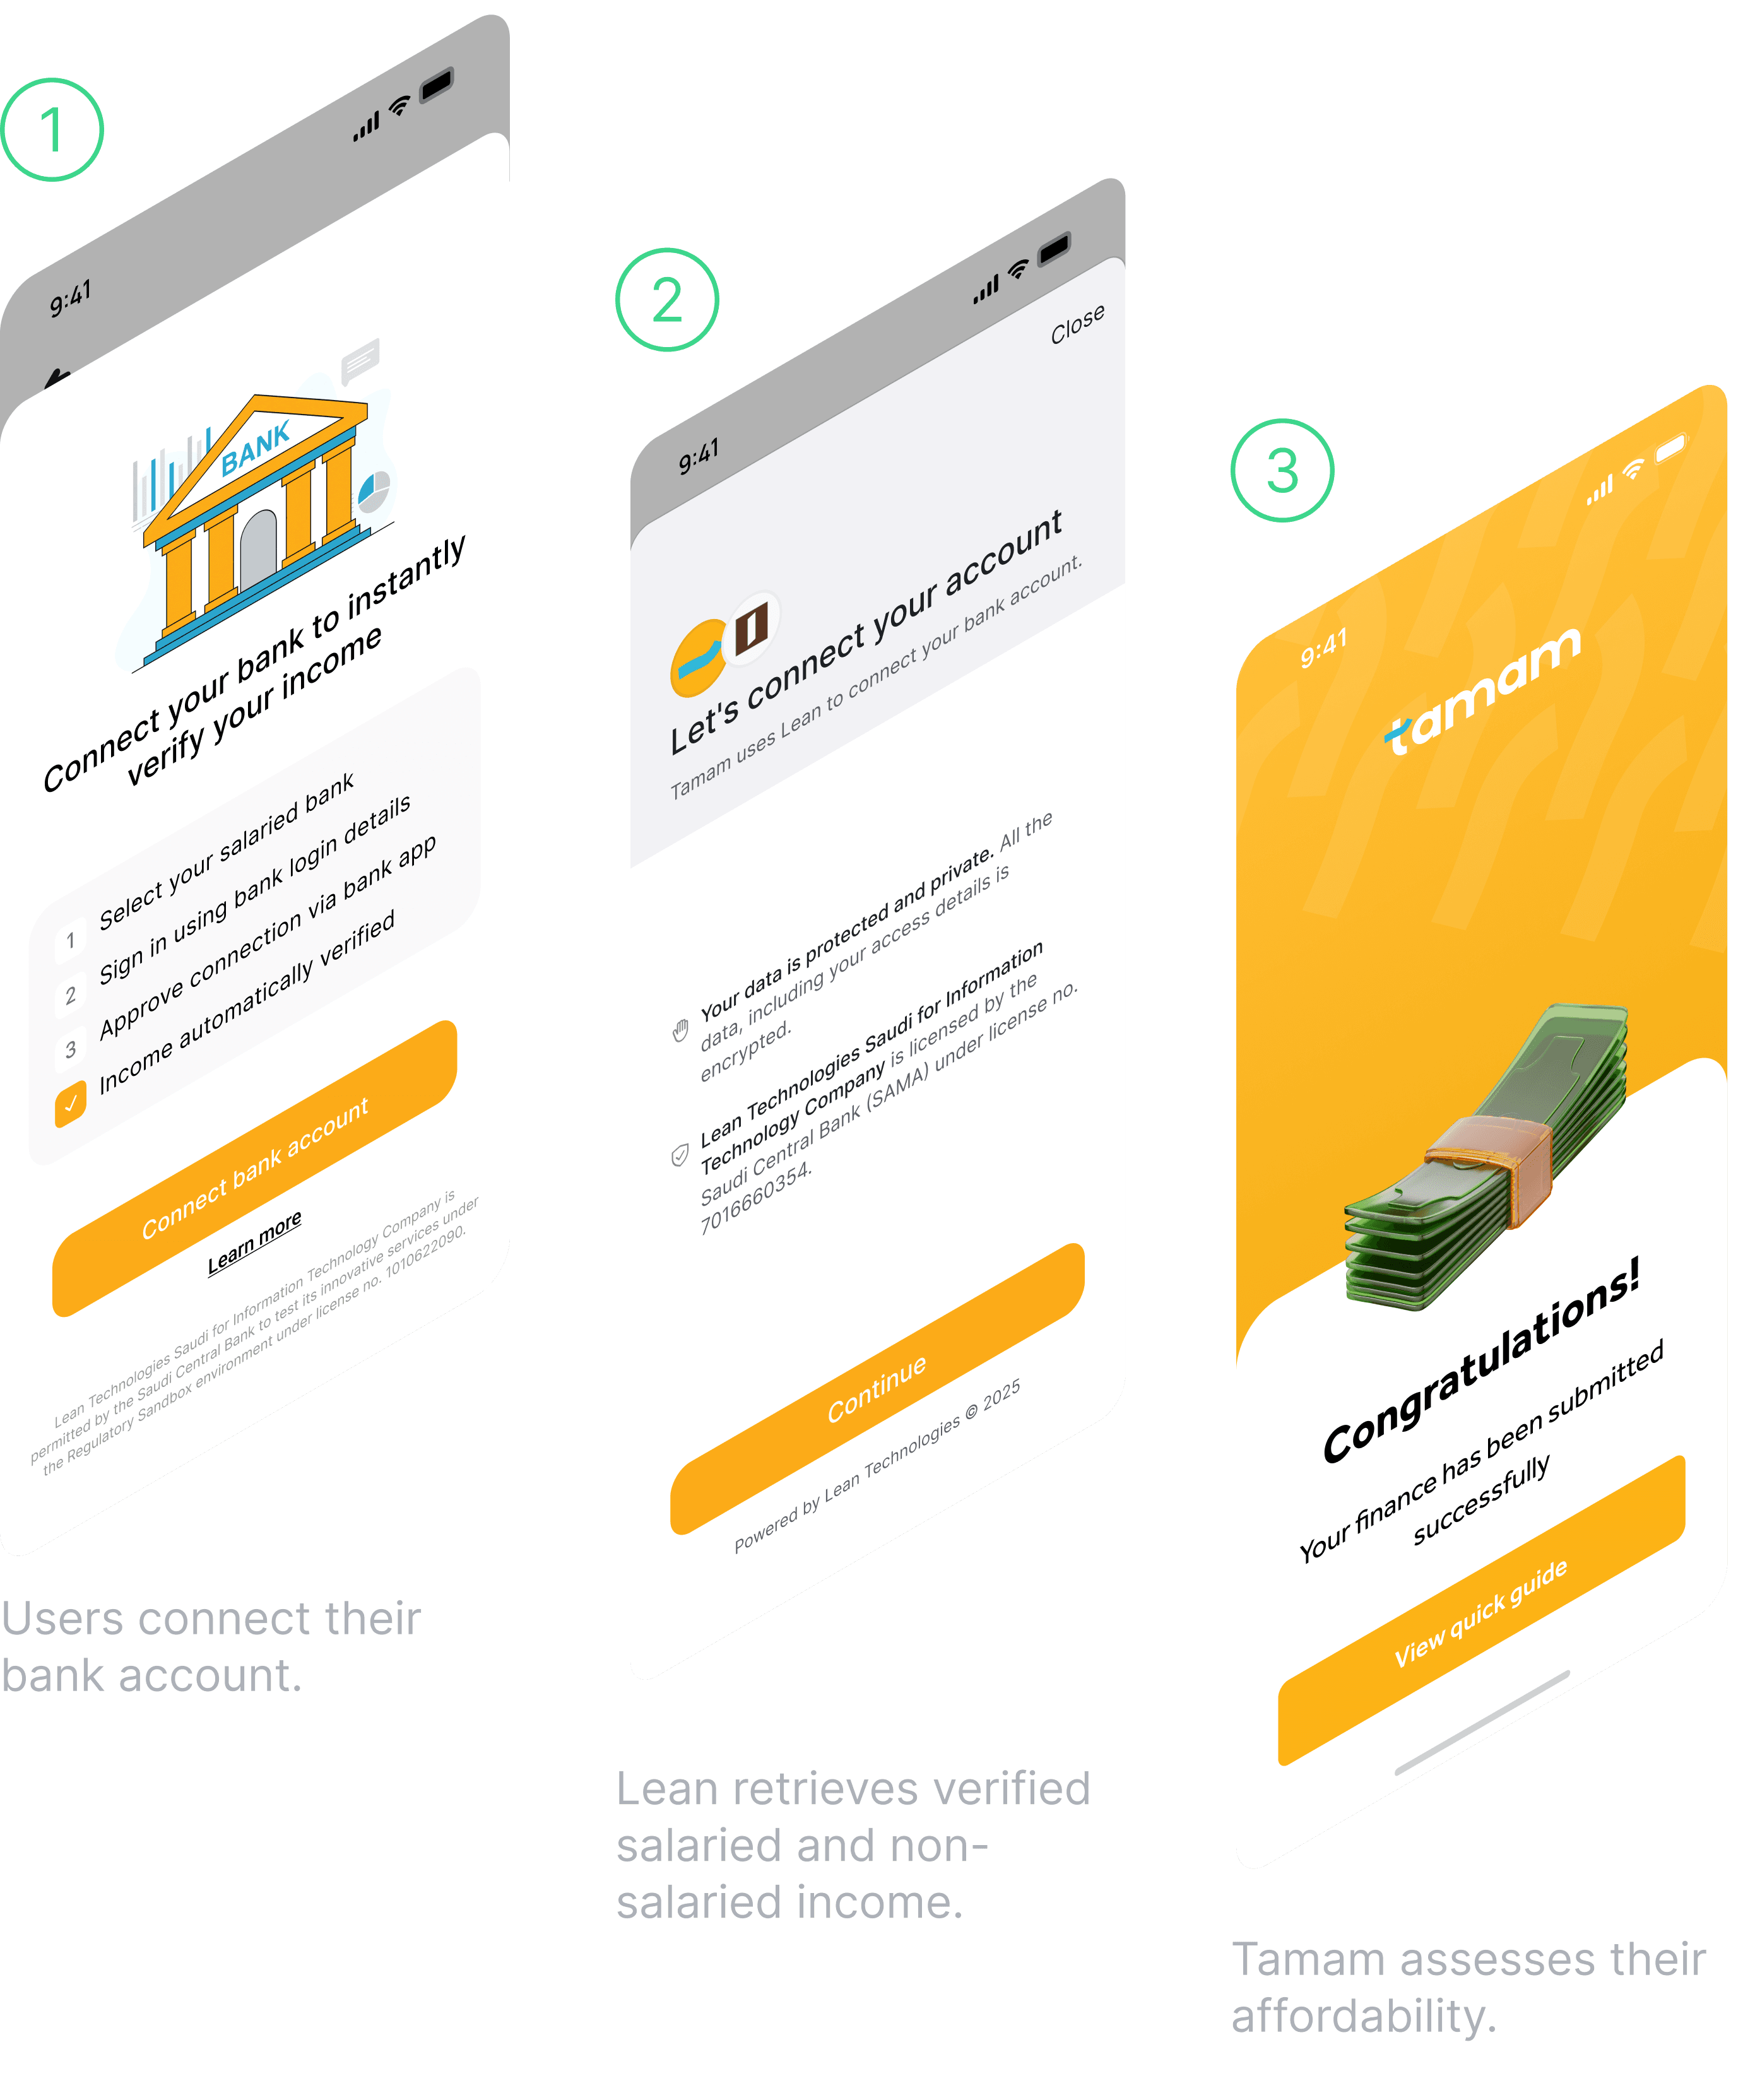
Applicants securely connect their bank account through a single Open Banking consent, giving Tamam access to verified financial data directly from the source. Lean transforms the raw bank data into structured income insights, surfacing both salaried and non-salaried income to provide a more complete view of each applicant's financial position.
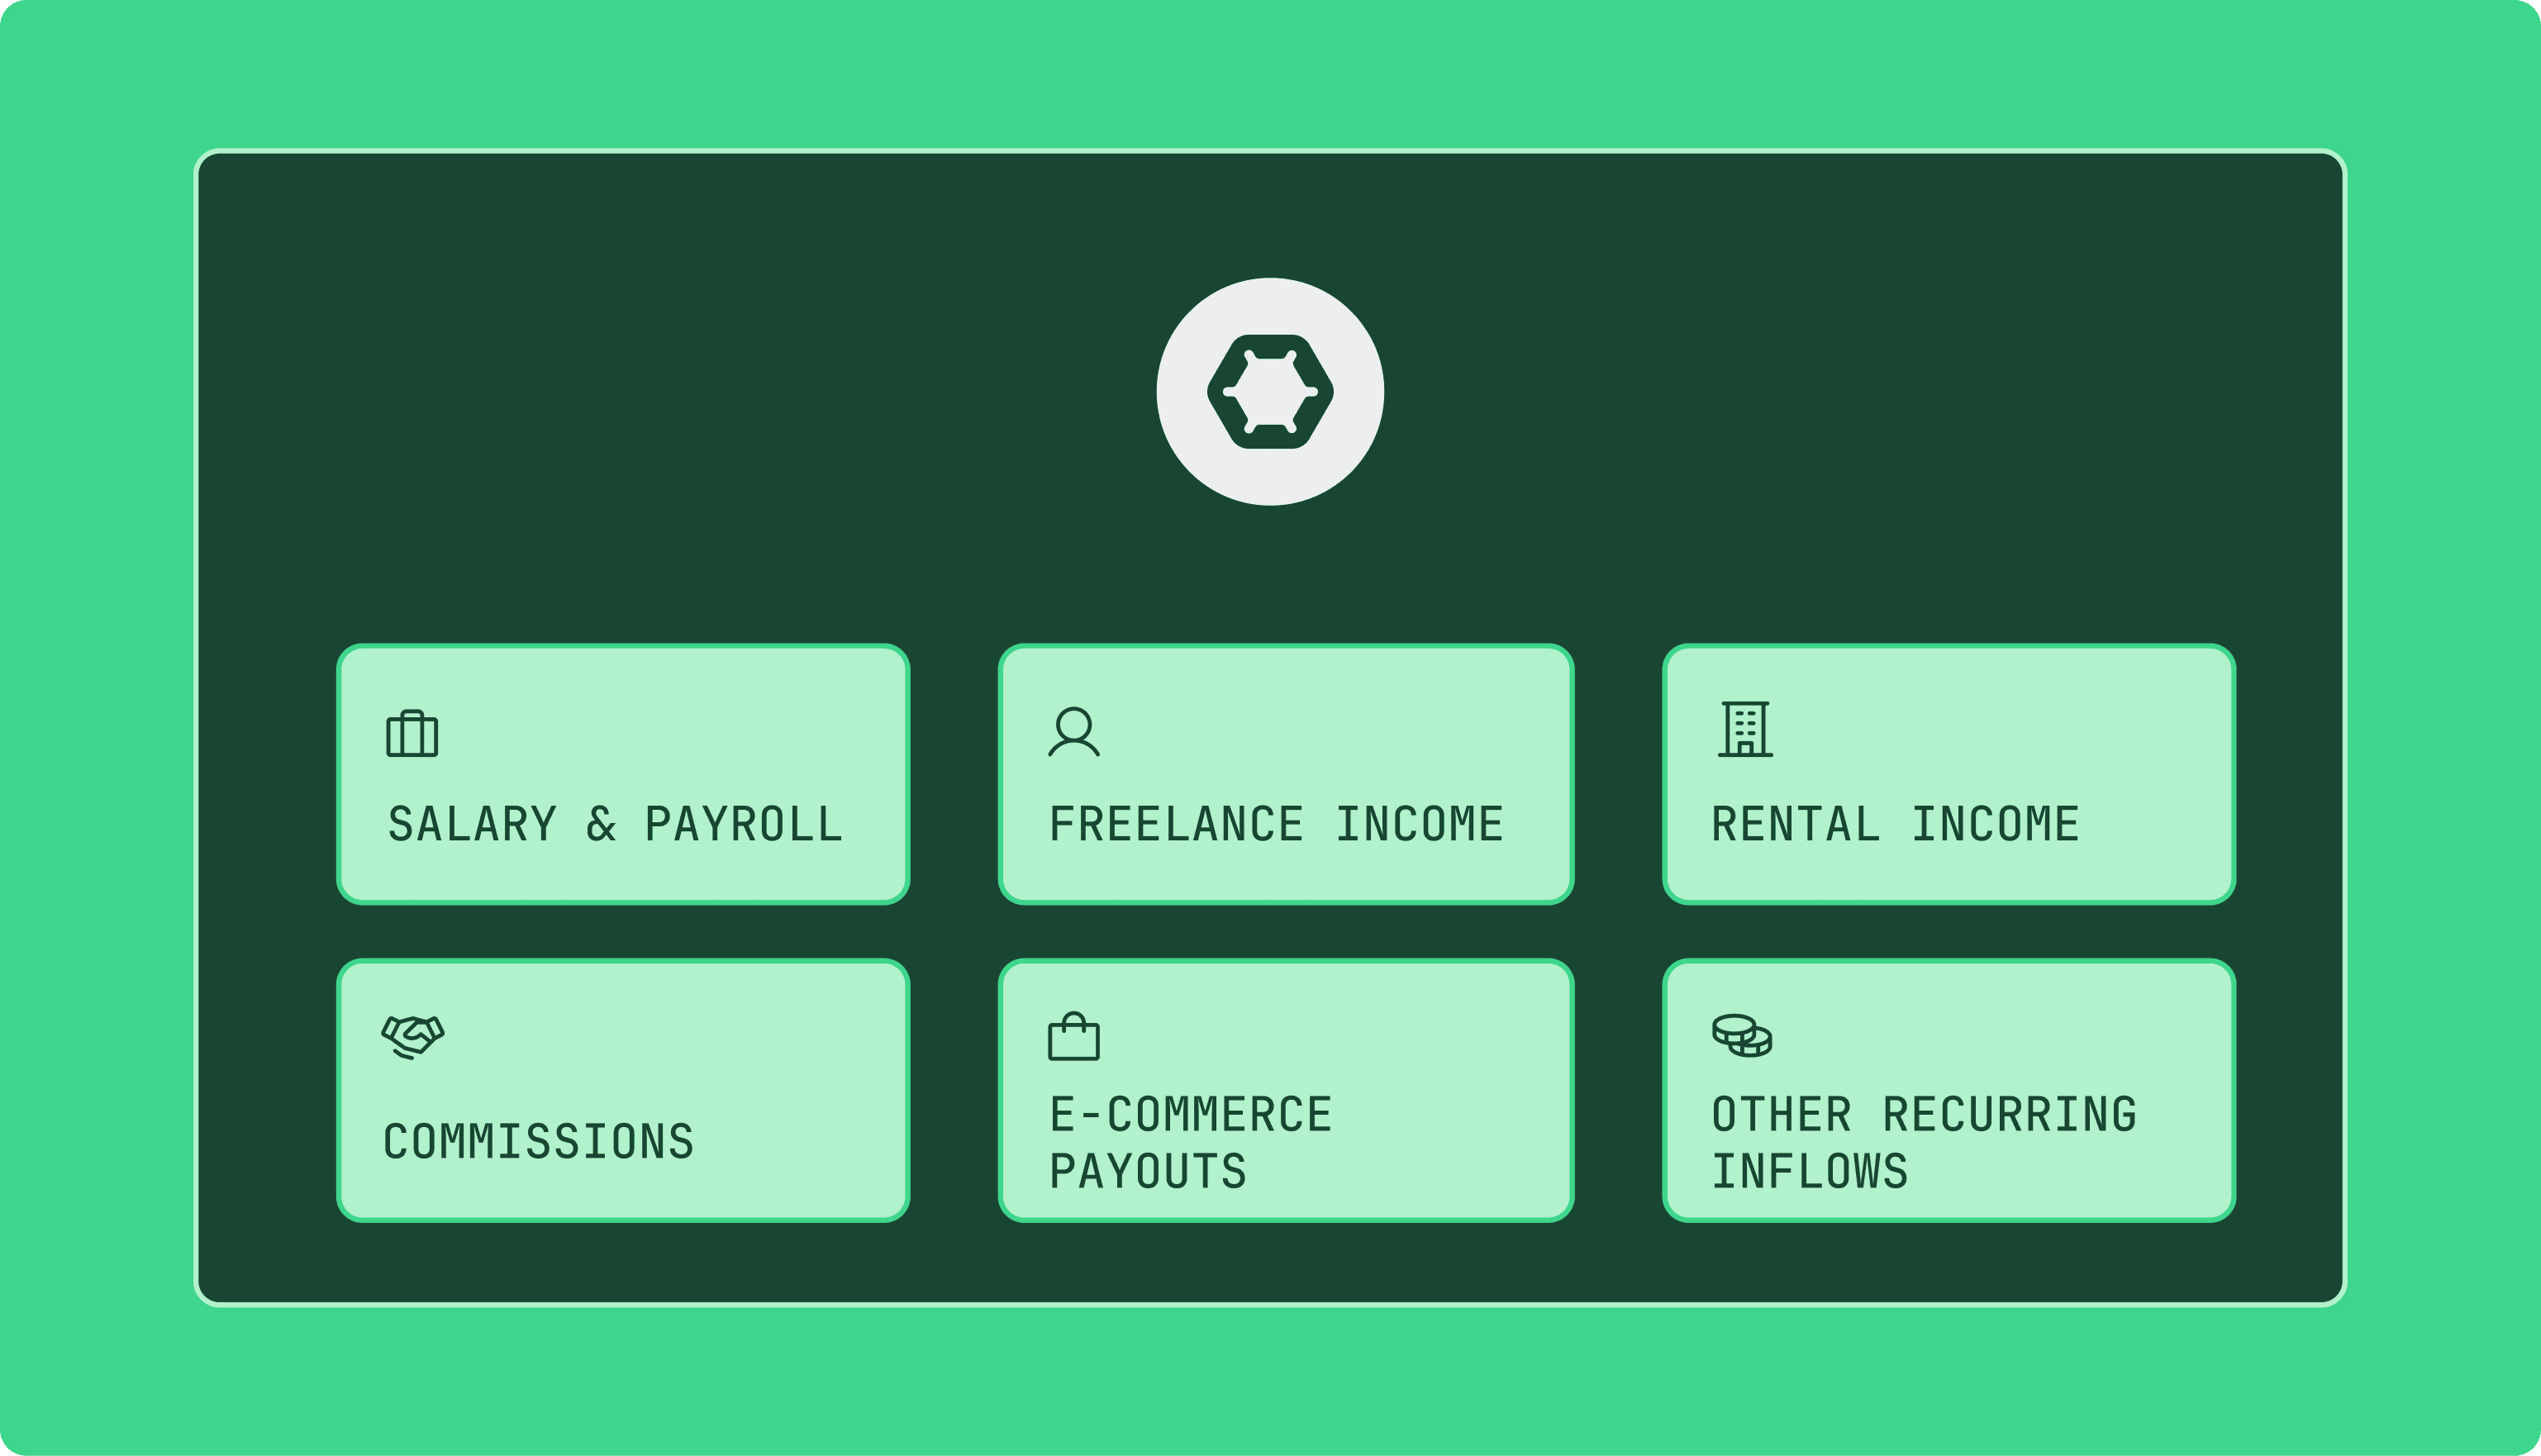
Through Lean, Tamam gained consent-based visibility into:
- Salary and recurring payroll deposits
- Freelance and professional service income
- Rental income
- Commissions and variable pay
- Digital marketplace and e-commerce settlements
- Recurring transfers and other regular inflows
Adoption has been strong even when connecting is optional: around 22% of applicants choose to share their financial data voluntarily during the application journey, signaling that customers are willing to trade a few seconds of consent for a fairer assessment.
By incorporating verified salary and non-salary income into its underwriting process, Tamam can base lending decisions on a broader view of affordability rather than reported salary alone. This has enabled Tamam to approve more creditworthy applicants while also offering credit limits that better reflect each customer's financial position.
Results
By bringing verified financial data into its underwriting process, Tamam has expanded responsible access to credit while improving the speed and consistency of its lending decisions.
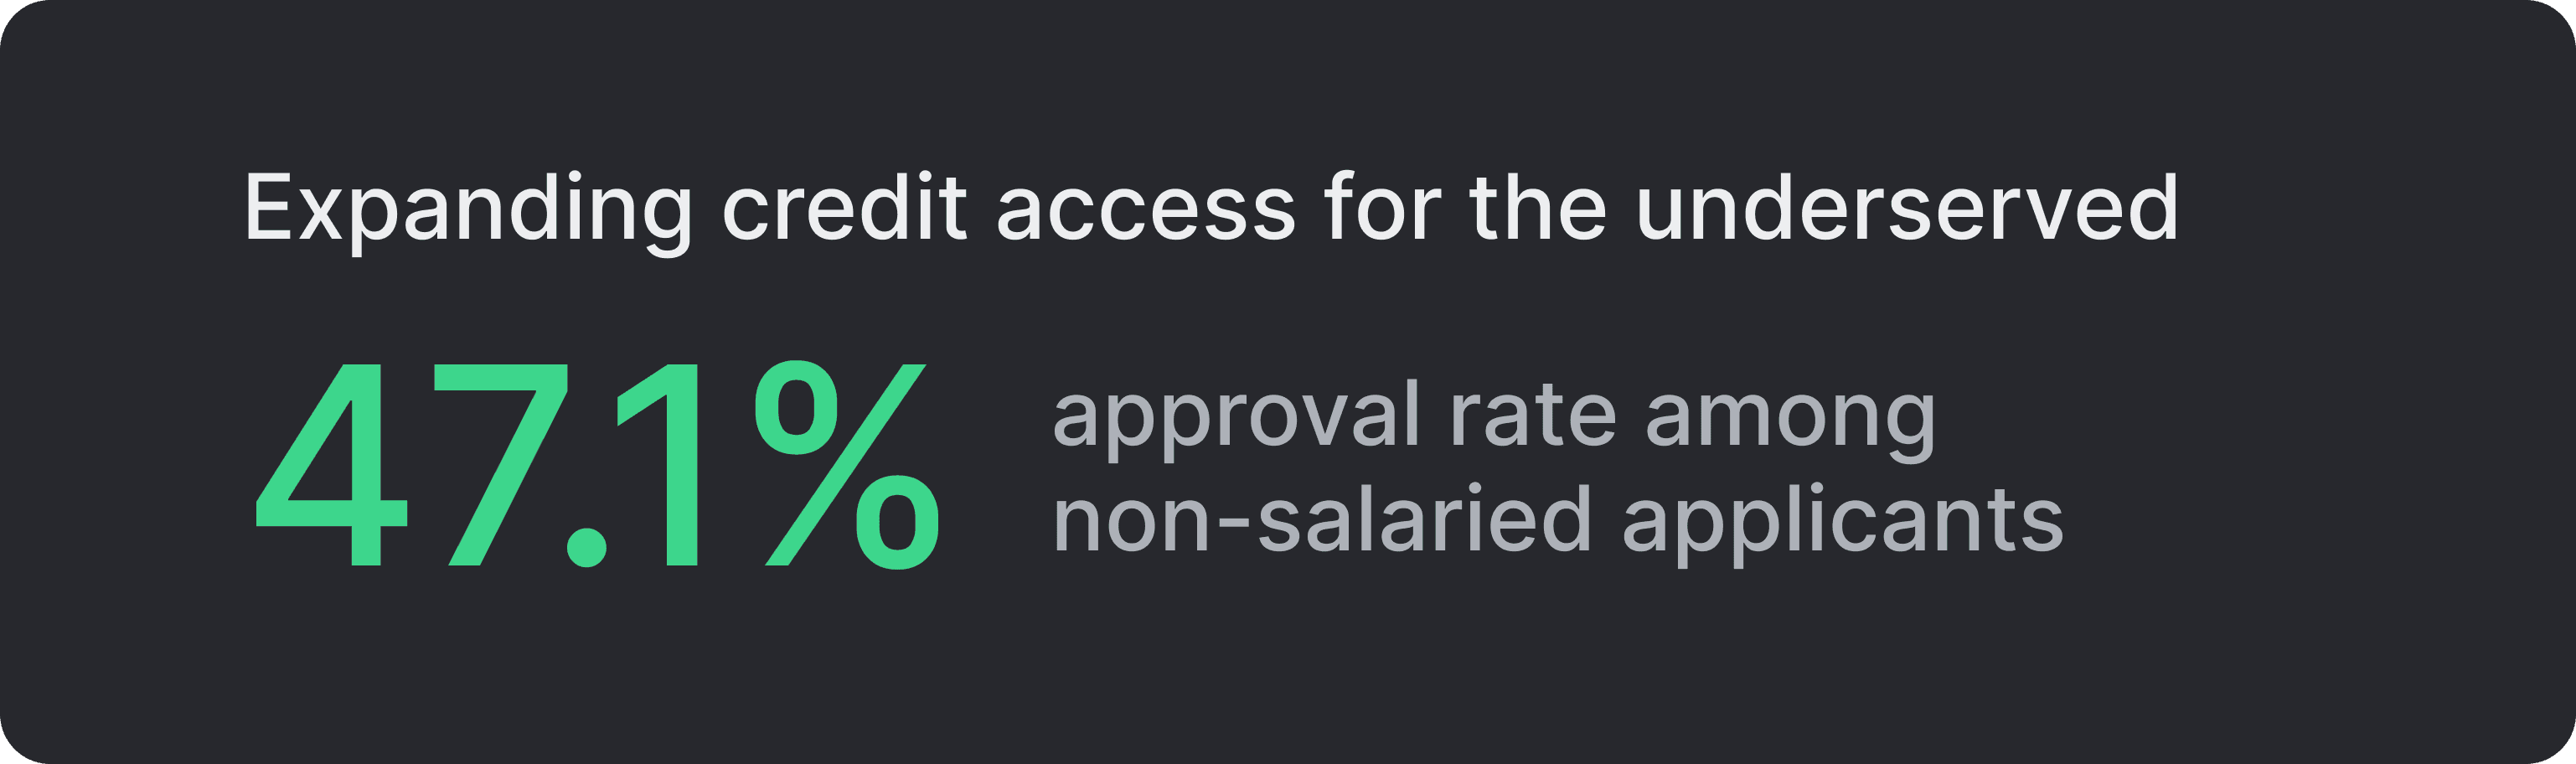
47.1% approval rate among non-salaried applicants
Verified income gives Tamam the confidence to approve applicants whose affordability was never fully reflected in traditional salary data, expanding responsible access to credit for nearly half of a segment that had previously been difficult to underwrite.
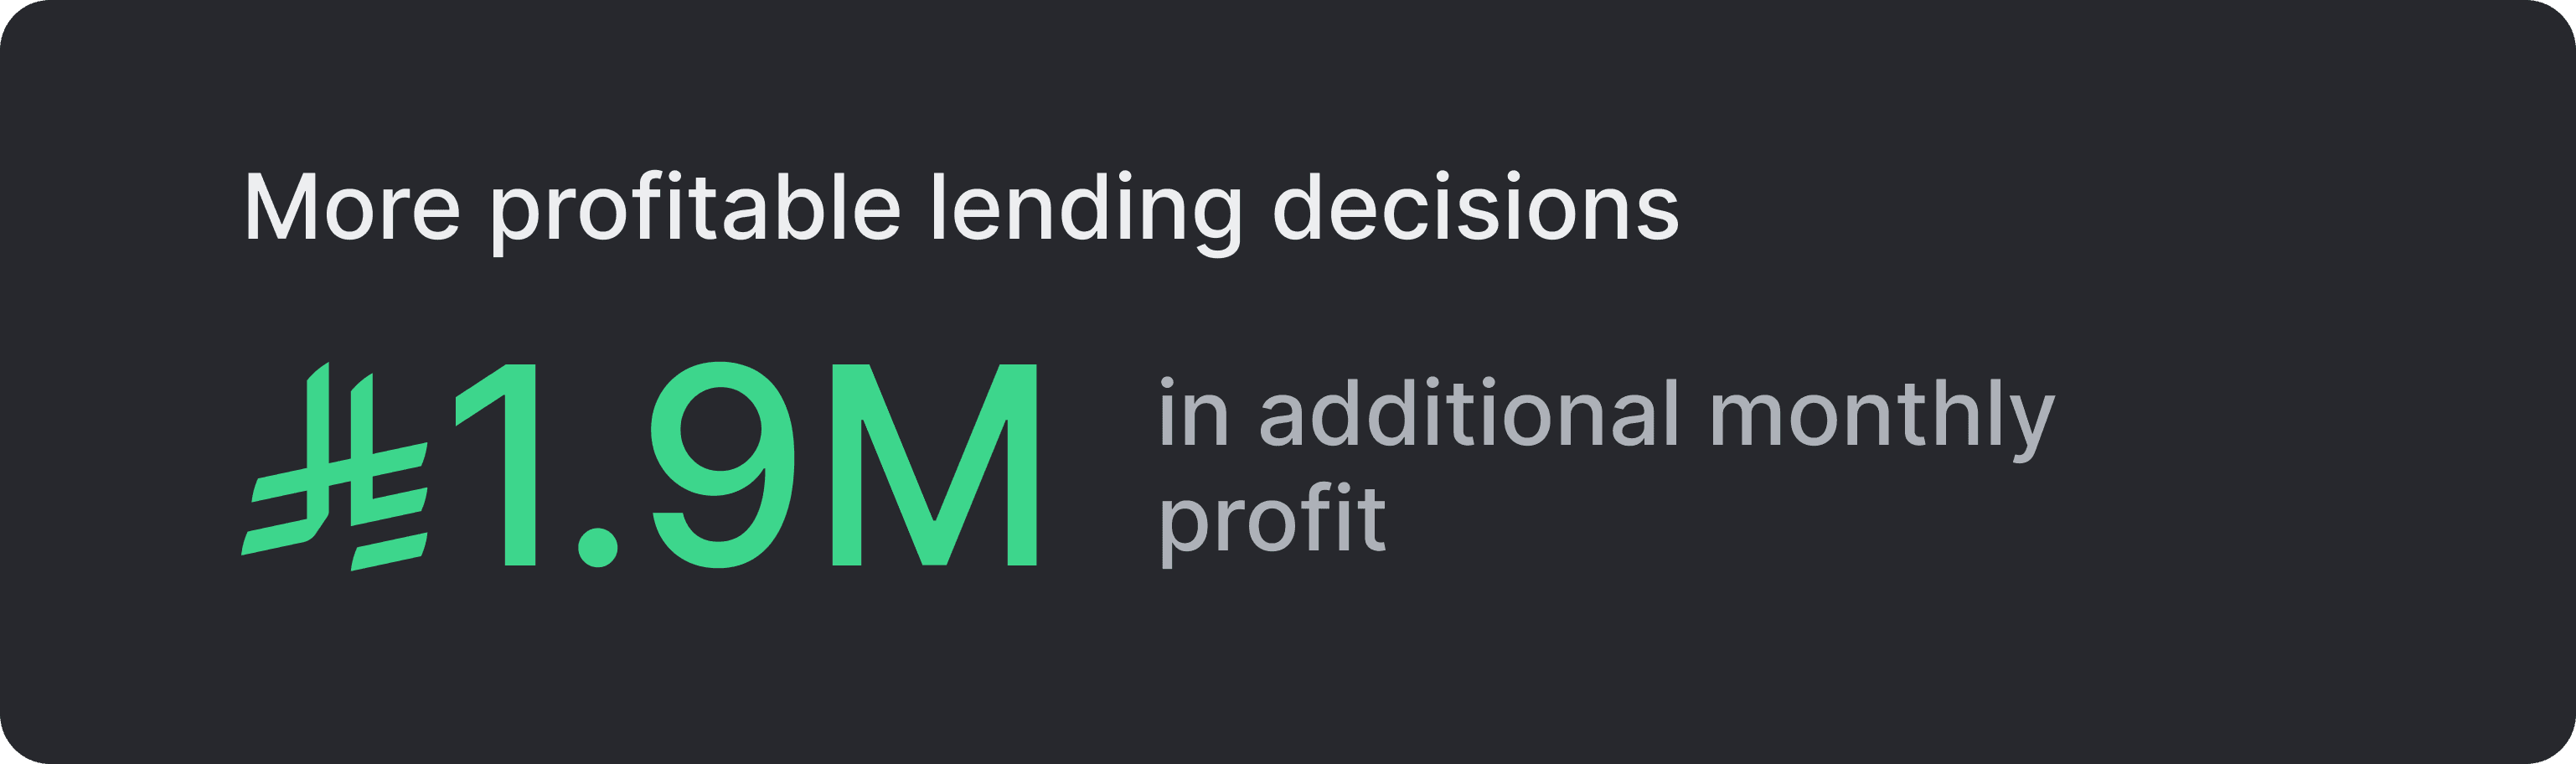
SAR 1.9M in additional monthly profit
Better lending decisions, powered by richer income visibility, generate approximately SAR 1.9 million in additional monthly profit.
Next Phase: Second Look Lending & Freelancer Verification
Today, customers can choose to connect their bank account during the application journey, allowing Tamam to assess affordability using verified income from the outset.
The next phase of the partnership introduces a dedicated second look lending journey, opening up an entirely new audience: applicants who were declined because the data available at the time told an incomplete story. Rather than treating a decline as final, Tamam can invite these customers to securely share their financial data through Lean and reassess affordability on verified income, extending responsible credit to customers who would otherwise have remained out of reach.
Alongside this, Tamam is working towards verifying freelancer certificates as part of the same assessment, adding official confirmation of self-employed status to the income picture Lean already surfaces. Together, the two give Tamam a firmer basis on which to price for a segment the market has long underserved.